VA Loans for Manufactured and Modular Homes: The Foundation Rule, the Shorter Term, and Why Lenders Say No
8 min read · Last updated September 17, 2026
Reviewed for accuracy by Steven Sun · See our Editorial Standards
- The U.S. Department of Veterans Affairs (VA) will only guarantee a manufactured home purchase when the home is permanently affixed to the lot and classified as real property under state law, not resting on blocks or a temporary support (38 Code of Federal Regulations (CFR) § 36.4301).
- The maximum loan term is shorter than a standard VA mortgage: 20 years and 32 days for a single-wide manufactured home, 23 years and 32 days for a double-wide alone, or 25 years and 32 days for a double-wide plus lot, versus up to 30 years and 32 days for a site-built home (38 CFR 36.4204(f)).
- You don’t have to buy the land and the home together. VA specifically allows a separate, shorter loan just to buy a lot for a manufactured home you already own (38 CFR 36.4204(a)(1)).
- A manufactured home loan draws from the same VA entitlement you’d use on any other VA-guaranteed loan. There’s no separate manufactured-home entitlement pool (38 CFR 36.4203(b)).
A VA loan can finance a manufactured or modular home only once it’s permanently attached to the lot and legally treated as real property, and even then the loan term tops out well short of 30 years: 20 years and 32 days for a single-wide, 23 to 25 years and 32 days for a double-wide, depending on whether the lot is included.
In this article
- What VA allows for a manufactured or modular home
- The permanent-foundation requirement
- Why the loan term is shorter than a site-built VA mortgage
- Financing the land with the home, or land you already own
- Why many lenders still won’t write this loan
- How your entitlement and loan limit apply
- Finding a lender who will actually originate the loan
- Frequently asked questions
Picture a veteran who already owns a paid-off, half-acre lot outside Amarillo, Texas, and wants to place a new single-wide manufactured home on it using a VA loan. A lender can approve the loan; VA does guarantee it. What that veteran won’t get is the 30-year term a site-built VA mortgage would carry. VA caps a single-wide manufactured home loan at 20 years and 32 days, a full 10 years shorter than a standard VA-guaranteed mortgage, even though both loans carry the same government backing.
What VA allows for a manufactured or modular home
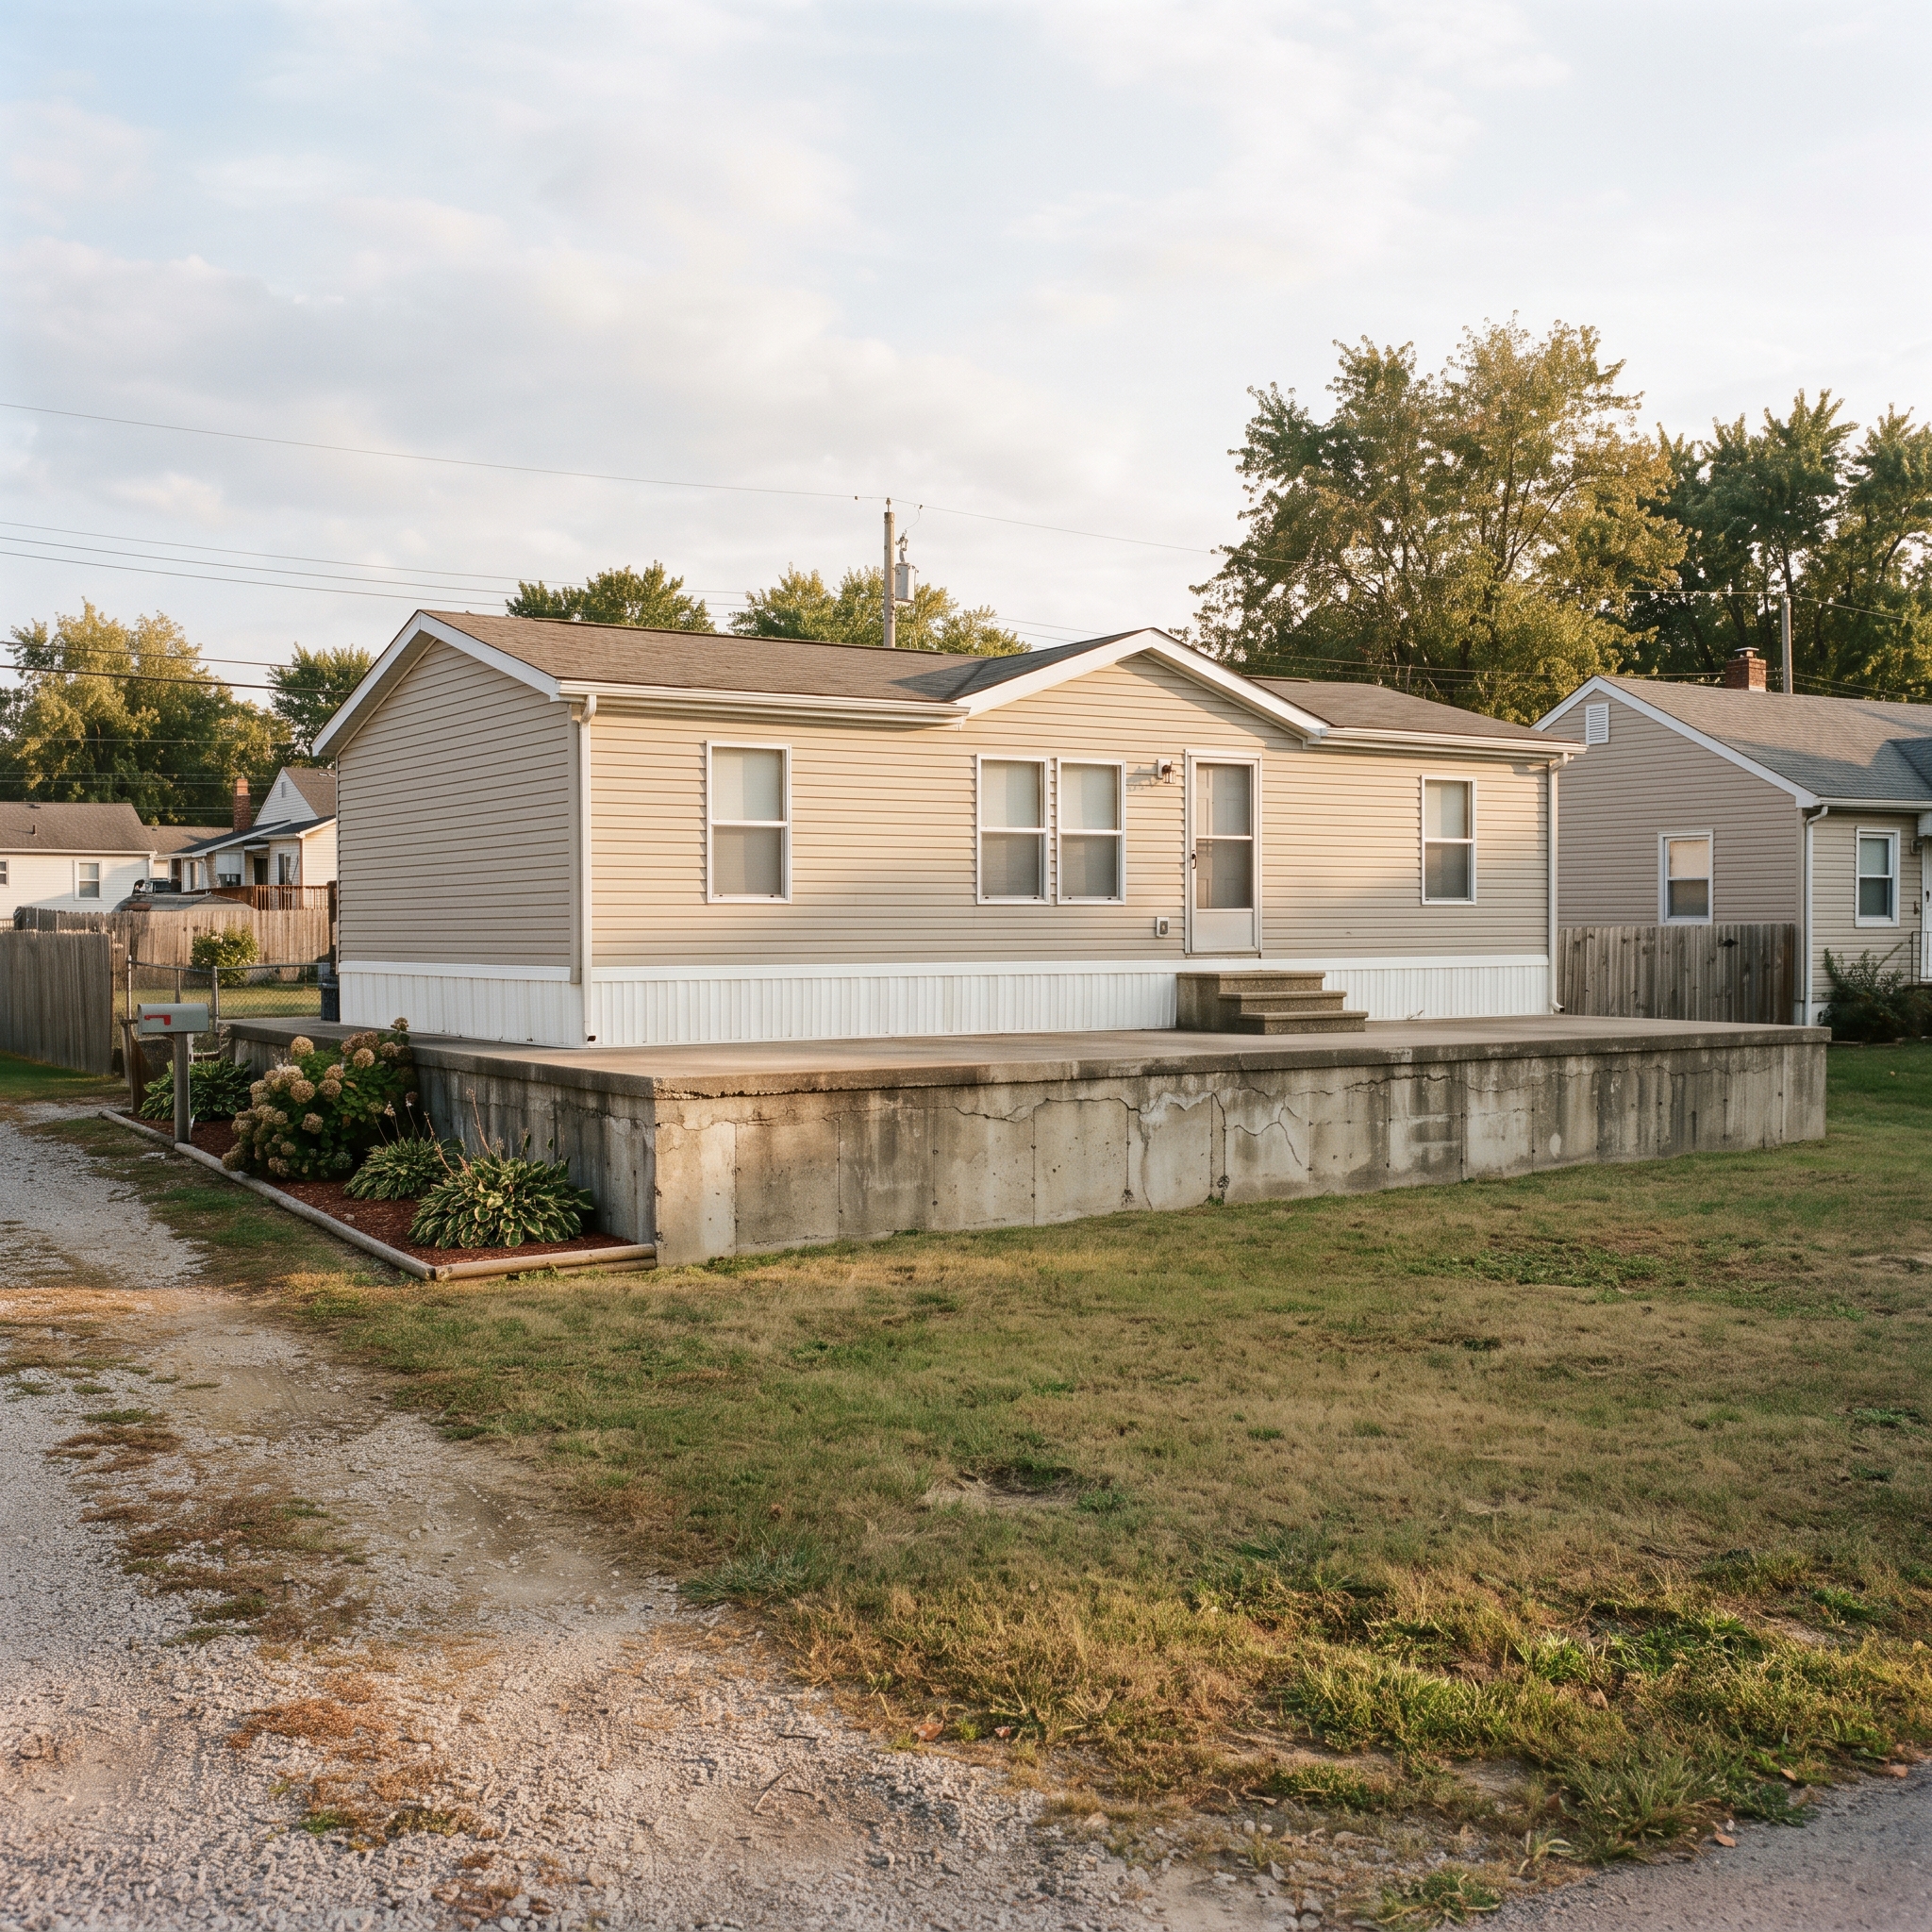
VA-backed purchase loans can be used to buy a manufactured home, a lot to place one on, or a manufactured home and lot together (VA.gov). But “manufactured” and “modular” are not interchangeable, and the difference changes which rules apply. A modular home is built off-site in sections to the same state and local building codes that govern a site-built house, then assembled on a permanent foundation. Once it’s installed, VA and most lenders treat it exactly like any other site-built home, standard 30-year term included. A manufactured home is built to the U.S. Department of Housing and Urban Development (HUD) Code (the federal construction standard that replaced the old “mobile home” label) on a steel chassis, and it’s this property type that triggers VA’s separate, shorter loan-term schedule, even after it’s permanently attached to the ground. If you’re not sure which category your home falls into, ask the manufacturer for the HUD data plate or certification label; a true modular home won’t have one, because it was never built to the HUD Code in the first place.
The permanent-foundation requirement
VA’s regulations define an eligible “housing unit” to include “a manufactured home, permanently affixed to a lot owned by a veteran and classified as real property under the laws of the State where it is located” (38 CFR 36.4301). In plain terms, the home has to be fixed in place, not sitting on temporary blocks or a hitch, and the state has to legally recognize it as real estate rather than as titled personal property, the way it’s classified the moment it leaves the factory. VA reinforced the same line in a 2016 circular governing what happens if a manufactured home loan goes to foreclosure: a manufactured home “must be permanently affixed and classified as real property in the state where it is located,” or VA cannot guarantee the loan under the standard home loan program at all (VA Circular 26-16-24). Converting a manufactured home from personal property to real property is a state-level paperwork process, typically involving the state’s motor vehicle or manufactured-housing division, and it has to happen before a lender will order an appraisal, not after.
Why the loan term is shorter than a site-built VA mortgage
Even after a manufactured home clears the foundation and real-property hurdle, VA’s own maximum loan terms remain shorter than a standard mortgage. The ceiling depends on the home’s width and whether the lot is part of the loan.
| Property configuration | Maximum VA loan term |
|---|---|
| Site-built home (standard VA loan) | Up to 30 years and 32 days |
| Single-wide manufactured home only | 20 years and 32 days |
| Single-wide manufactured home and lot | 20 years and 32 days |
| Double-wide manufactured home only | 23 years and 32 days |
| Double-wide manufactured home and lot | 25 years and 32 days |
| Lot only (home already owned by the veteran) | 15 years and 32 days |
The extra 32 days in every figure isn’t a typo; it’s a standard VA underwriting buffer built into the regulation itself, giving a small cushion past the exact year mark. The practical effect of the shorter term is a higher monthly payment for the same loan amount than a 30-year site-built mortgage would carry, since less time means less room to spread out principal. A modular home that’s been built to local code and installed on a permanent foundation doesn’t fall under this table at all; it’s underwritten on the standard 30-year schedule because VA doesn’t treat it as a manufactured home in the first place.
Financing the land with the home, or land you already own
The land does not have to be purchased together with the manufactured home. VA’s own list of allowable loan purposes includes buying a manufactured home and a lot in a single loan, but it separately lists as an allowable purpose a loan “to purchase a lot on which to place a manufactured home already owned by the veteran” (38 CFR 36.4204). That lot-only configuration carries its own, even shorter 15-year-and-32-day term, since the loan is smaller and the risk profile is different. In practice this covers three real situations: buying the home and the land together as one transaction, buying only the land because you already own or are purchasing the manufactured home separately, or refinancing an existing manufactured home loan once you’ve since acquired the lot. Whichever path applies, VA still requires the lot itself to meet its own site standards, including an acceptable state of repair for utilities, drainage, and access before a loan can close.
Why many lenders still won’t write this loan
VA’s willingness to guarantee a manufactured home loan doesn’t obligate any individual lender to originate one, and a meaningful share of VA-approved lenders simply don’t offer this product. Two mechanical reasons drive that gap, not a lack of demand. A 20-to-25-year manufactured home loan doesn’t fit neatly into the standard 30-year mortgage-backed securities pipeline most lenders are built around, since it behaves differently on the secondary market. And underwriting one takes more specialized steps than a typical purchase: confirming the foundation, verifying the state’s real-property reclassification, and applying VA’s separate manufactured-home underwriting standards, on top of the usual appraisal and credit review. Lenders that don’t originate many of these loans have little incentive to build out that expertise for a small slice of their VA volume.
How your entitlement and loan limit apply
A manufactured home loan doesn’t draw from a separate pool of benefits. Sections 3710, 3711, and 3712 of Title 38 of the United States Code (U.S.C.), covering standard home purchases, direct loans to veterans in underserved rural areas, and manufactured home and lot purchases respectively, pool into one shared entitlement. VA’s own rule states that “a veteran may use his or her remaining home loan guaranty entitlement for any purpose authorized by” all three sections (38 CFR 36.4203). The same entitlement and county loan-limit mechanics covered in our full guide to VA loan limits and entitlement apply here without modification. One manufactured-home-specific wrinkle worth knowing: VA generally won’t guarantee a second manufactured home loan for the same veteran until the home securing the first loan has been disposed of or destroyed, a restriction that doesn’t exist for site-built home purchases.
Finding a lender who will actually originate the loan
Start by getting your Certificate of Eligibility in hand before you shop, since a lender can’t quote you accurately without confirming your entitlement first. When you call a lender, ask directly whether they originate VA loans on manufactured homes classified as real property, not just whether they do VA loans in general; the two questions get very different answers. Credit unions and regional banks that already work with manufactured-housing dealers in your area are more likely to have this expertise than a large national retail lender. Whoever you work with, expect the same VA appraisal and minimum property requirement review that applies to any VA purchase, plus the added step of confirming your home’s real-property status with the state before the loan can close.
Frequently asked questions
Can I get a VA loan for a manufactured home that isn’t attached to a foundation yet? Not through VA’s standard home loan program. The home has to be, or be in the process of becoming, permanently affixed to the lot and classified as real property under your state’s law. A home still titled as personal property has to complete that reclassification before a lender can move forward.
Do I have to buy the land and the manufactured home at the same time? No. VA allows a combined purchase, but it also allows a separate loan just for a lot if you already own the manufactured home, or separate financing for the home if you already own the land. Each configuration has its own maximum loan term.
Why can’t I find a 30-year VA loan for my manufactured home? VA’s maximum terms for manufactured homes top out at 20 to 25 years depending on width and whether land is included, well short of the standard 30-year term for a site-built home. A modular home built to local code and set on a permanent foundation isn’t subject to this shorter schedule.
Does financing a manufactured home use up more of my VA entitlement than a regular home loan? No. Manufactured home loans draw from the same overall entitlement as any other VA-guaranteed loan. The county loan limit and entitlement math work the same way; only the maximum loan term and property rules differ.
Why do some VA-approved lenders refuse to do manufactured home loans at all? The shorter amortization schedule doesn’t fit standard mortgage-backed securities pipelines, and underwriting a manufactured home loan requires extra steps most lenders don’t build expertise around for a small share of their VA volume. VA allowing the loan doesn’t require any specific lender to offer it.