The Department of Veterans Affairs Loan Program Where It Is the Lender, Not the Bank
5 min read · Last updated August 22, 2026
- The Native American Direct Loan (NADL), a Department of Veterans Affairs (VA) program, charges a flat 1.25% funding fee on a purchase, no matter your down payment or whether you have used a VA loan before.
- VA is the direct lender on a NADL, not a private bank or mortgage company, which is different from every other VA loan type.
- Your home must sit on land covered by a Memorandum of Understanding (MOU) between VA and a federally recognized tribal government. State-recognized-only tribes do not qualify.
- On a $350,000 loan, the NADL’s flat fee saves a repeat VA borrower up to $7,175 in funding fee compared to a standard VA loan with a low down payment.
In this article
- What the NADL program is
- Who qualifies
- What the loan covers
- How to apply
- What causes delays or denials
- Frequently asked questions
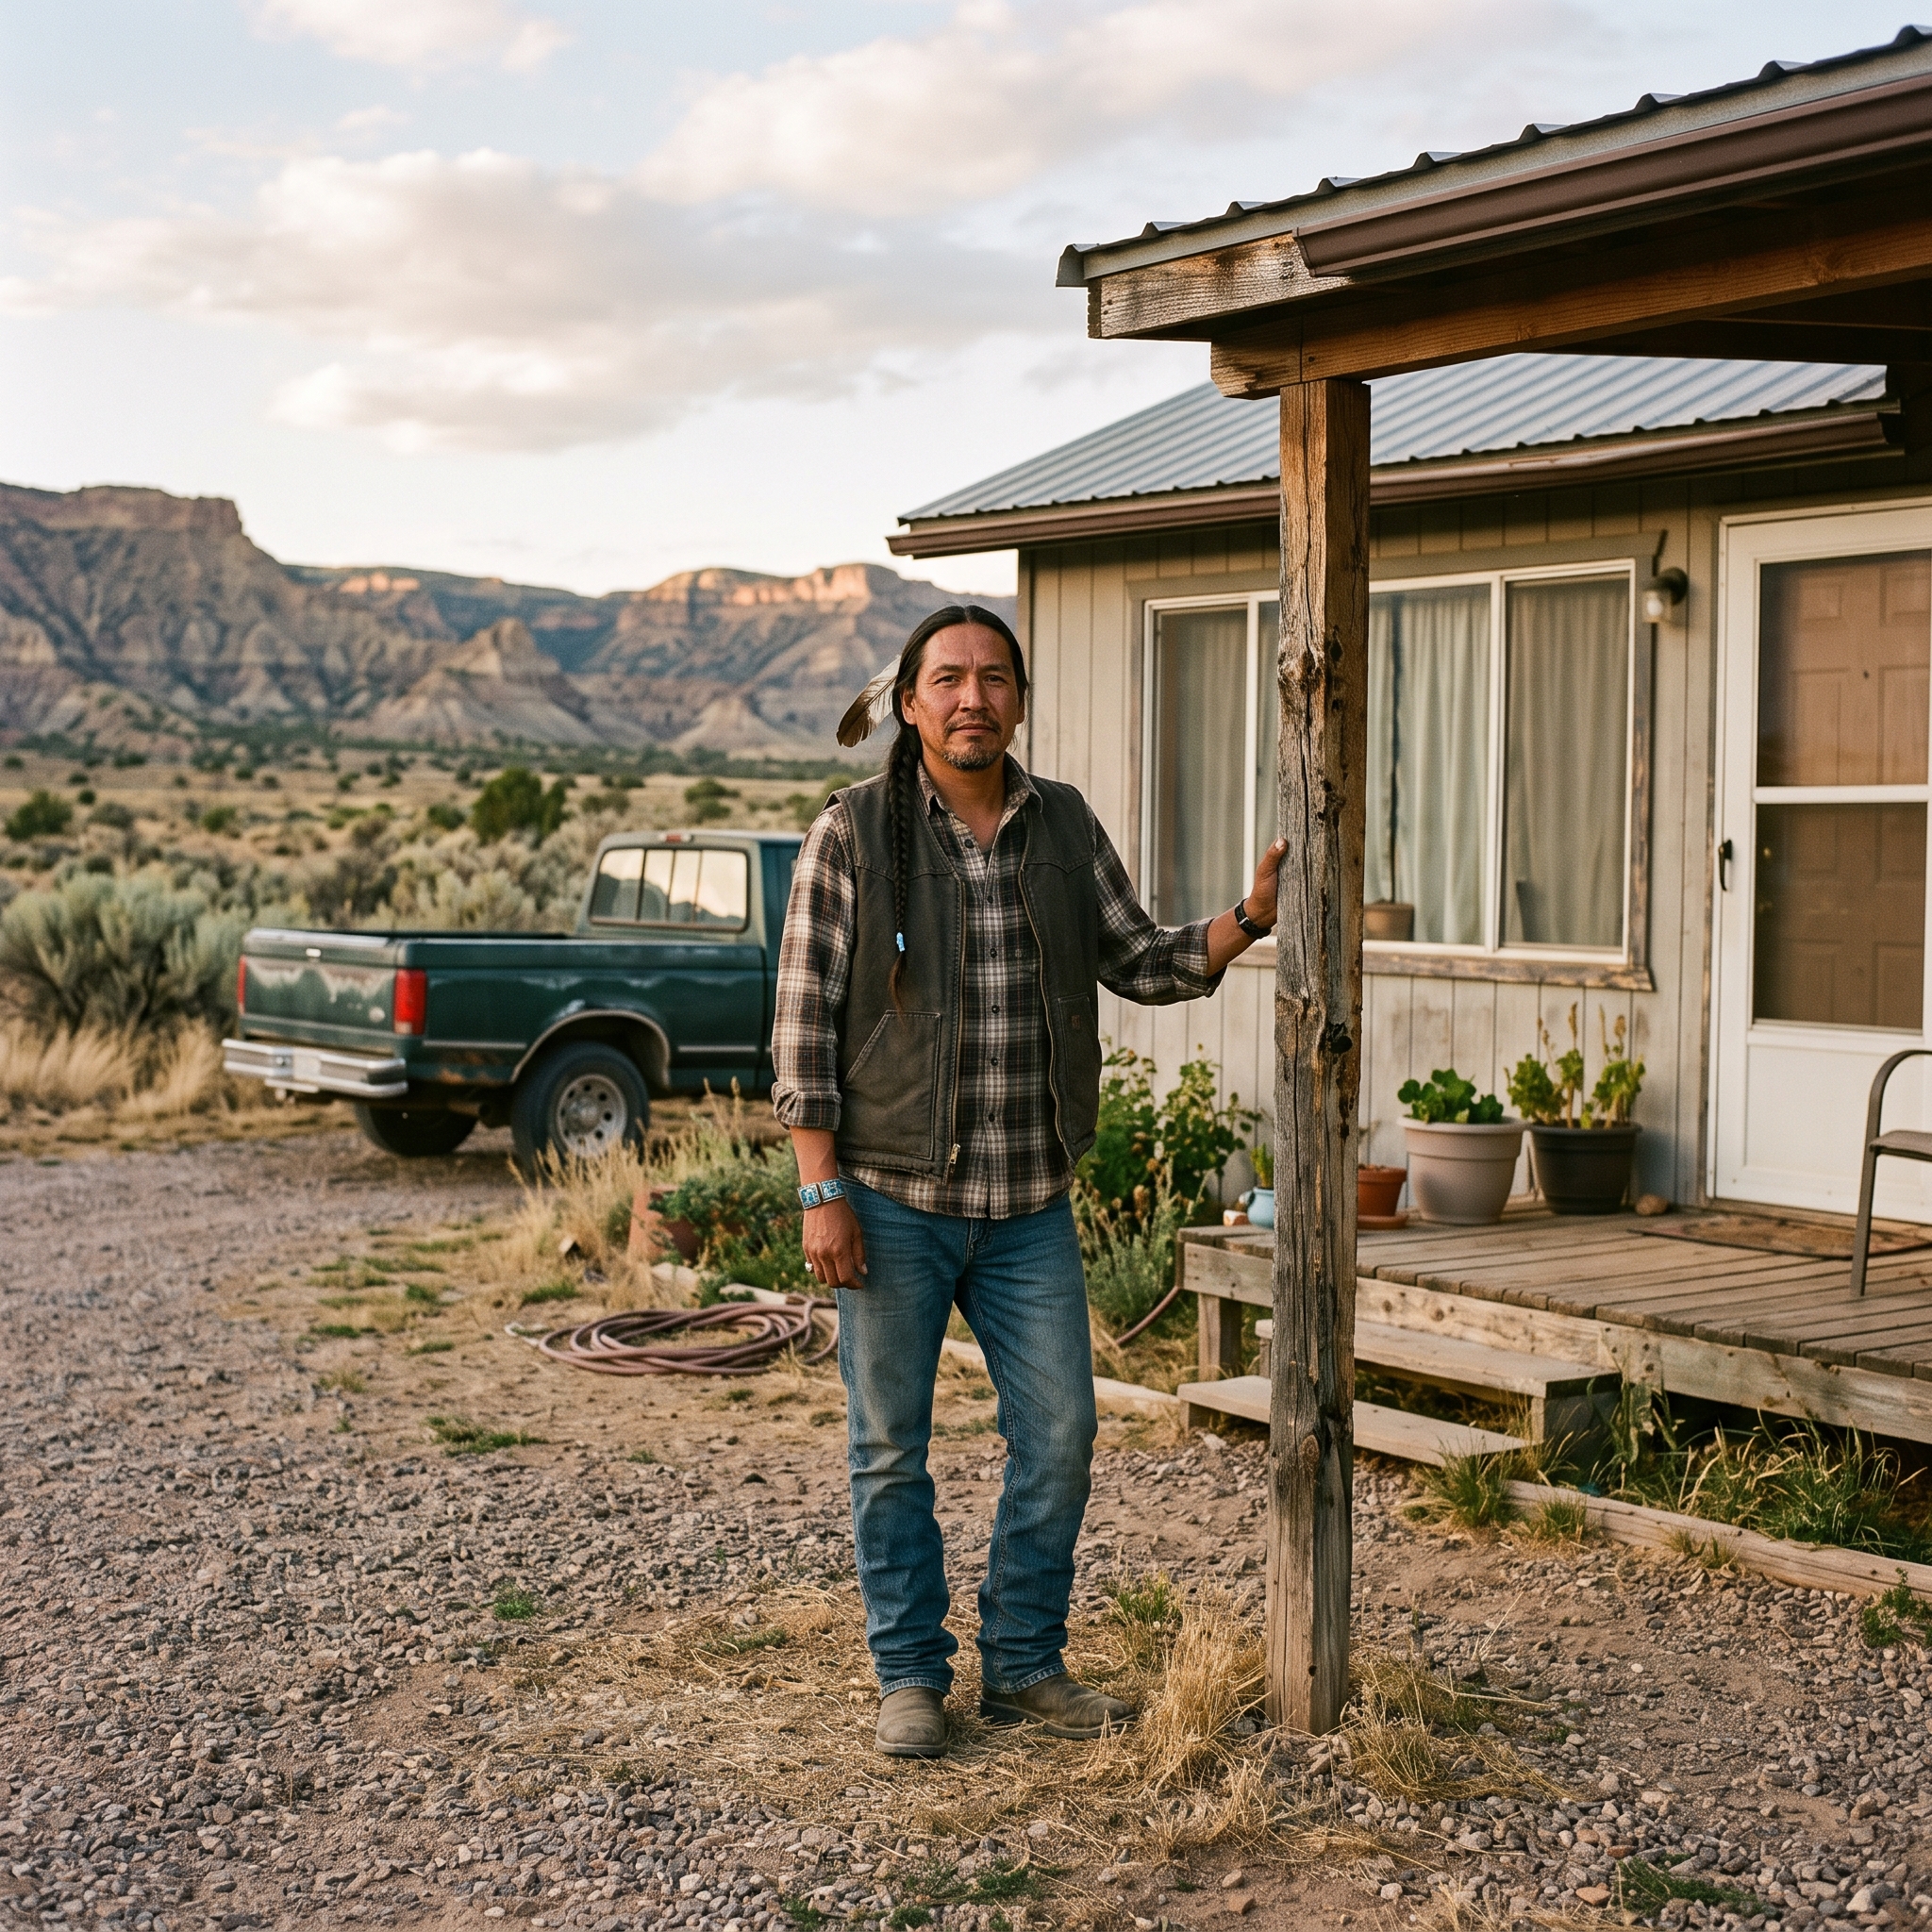
Robert Yazzie, a 34-year-old Army veteran and enrolled member of the Navajo Nation, wanted to build a home on his family’s allotment near Chinle, Arizona. A standard VA-backed loan would have charged him a 2.15% funding fee as a first-time user. Because his land is covered by an existing agreement between his tribe and the Department of Veterans Affairs (VA), he used the Native American Direct Loan (NADL) program instead, at a flat 1.25% fee.
What the NADL program is
The Native American Direct Loan is authorized under 38 United States Code (U.S.C.) § 3762, a section of federal law that lets VA make a direct home loan to a Native American veteran, or to a veteran married to a Native American, to buy, build, or improve a home on federal trust land. Trust land is property the U.S. government holds in trust on behalf of a tribe or an individual tribal member, rather than land the veteran owns outright the way most homeowners do. That distinction is exactly why NADL exists as its own program instead of a standard VA loan: a private lender generally will not take trust land as collateral because it cannot foreclose on it the normal way, so VA became the direct lender itself.
The funding fee reflects that structure. A standard VA-backed purchase loan charges 2.15% on a first use with less than 5% down, dropping to 1.5% at 5% down and 1.25% at 10% down, and it rises to 3.3% on any later VA loan with less than 5% down. The NADL purchase fee never moves. It is 1.25% every time, regardless of down payment or how many VA loans you have used before. A NADL refinance carries a 0.5% fee.
Who qualifies
Every condition below has to be true. VA and the tribal government must have signed an MOU covering your specific parcel of trust land. VA’s current MOU list runs to roughly 120 tribes and Native communities in total, including the Navajo Nation, the Hopi Tribe, the Gila River Indian Community, the Salt River Pima-Maricopa Indian Community, and American Samoa. A tribe recognized only by a state, not by the federal government, does not qualify no matter how strong the veteran’s other qualifications are.
You need a valid Certificate of Eligibility (COE), the same document that opens the door to any VA-backed loan. You must meet VA’s credit standards and show income sufficient to cover the mortgage and ordinary homeownership costs. You must plan to live in the home as your primary residence. Eligibility runs through two paths: you are a Native American veteran, or you are a veteran (of any background) married to a Native American who is not themselves a veteran.
If your tribe is not on VA’s current MOU list, that is not necessarily permanent. A tribal government can contact VA’s NADL team directly to start the process of establishing one.
What the loan covers
A NADL can purchase, build, or improve a home on eligible trust land, and it can refinance an existing NADL to get a lower rate. There is no fixed VA-set loan limit. Instead you can generally borrow up to the Fannie Mae and Freddie Mac conforming loan limit for your area with no down payment, and above that limit with a down payment, the same flexibility a standard VA loan borrower gets.
| Loan type | First use | Later use |
|---|---|---|
| NADL purchase | 1.25% | 1.25% |
| NADL refinance | 0.5% | 0.5% |
| Standard VA purchase, under 5% down | 2.15% | 3.3% |
| Standard VA purchase, 5% to 9.99% down | 1.5% | 1.5% |
| Standard VA purchase, 10% or more down | 1.25% | 1.25% |
Run the math on a $350,000 loan. A NADL purchase costs $4,375 in funding fee, flat. A standard VA purchase loan with 5% down at first use costs $5,250, a difference of $875. Drop to less than 5% down on a first-time standard VA loan and the fee climbs to $7,525, a $3,150 gap. Use a standard VA loan for a second time with less than 5% down and the fee reaches $11,550, a full $7,175 more than the NADL rate on the identical loan amount.
How to apply
Start with the same first step every VA loan applicant takes: request your COE through VA.gov or through an accredited representative. That part of the process is identical to a standard VA loan application.
From there, the path splits. Because VA itself is the lender, you do not shop for a private bank the way you would with a standard VA-backed loan. Instead, contact VA’s NADL team directly at nadl@va.gov or 1-888-349-7541 to start the application, and expect your tribal housing authority to be involved in verifying your land status. Bring documentation of your tribal enrollment or your marriage to an enrolled tribal member, along with proof of income and the usual credit documentation.
What causes delays or denials
The single most common reason a NADL application stalls is land that is not yet covered by an MOU. VA cannot approve a NADL on trust land until the tribal government and VA have signed that agreement, so a veteran with every other qualification in place can still be turned away simply because the paperwork between the two governments does not exist yet. If your tribe is not on the current list, ask your tribal housing office whether starting an MOU is already in progress.
Beyond that, the usual mortgage disqualifiers apply: insufficient income relative to the loan amount, credit history that does not meet VA’s standards, or an intent to use the home as anything other than a primary residence.
Frequently asked questions
Do I have to be enrolled in a federally recognized tribe to use a NADL? Yes, or you must be a veteran married to someone who is. The tribe also needs an active Memorandum of Understanding with VA covering the specific trust land. State-recognized-only tribes do not qualify, even if the veteran’s individual eligibility is otherwise solid.
Is the NADL funding fee really the same no matter how many times I have used a VA loan? Yes. The 1.25% purchase fee and 0.5% refinance fee do not change with down payment size or repeat use, which is different from standard VA loans, where the fee rises for later use with a low down payment.
Can I use a NADL if my tribe is not currently on VA’s MOU list? Not yet, but it is not necessarily closed off. Your tribal government can contact VA’s NADL team directly to start negotiating an MOU. Until that agreement exists, VA cannot approve a NADL secured by that land.
Does a NADL work the same way as getting a mortgage from a bank? No. VA is the actual lender on a NADL, not a guarantor of a private lender’s loan the way it is on every other VA loan type. You apply through VA’s NADL team rather than shopping among private mortgage companies.
What can a NADL actually pay for? Buying, building, or improving a home on eligible trust land, or refinancing an existing NADL for a better rate. It cannot be used for land that is not covered by an active tribal MOU with VA.